The global shipping and logistics industry is undergoing its most significant structural shift since the pandemic-era supply chain crisis. After years of volatile recovery, the freight market is transitioning from a recovery phase into a period of fundamental restructuring — characterised by more balanced capacity, uneven demand, and rapid technology adoption.
Ocean Freight: Excess Capacity Meets Slowing Demand
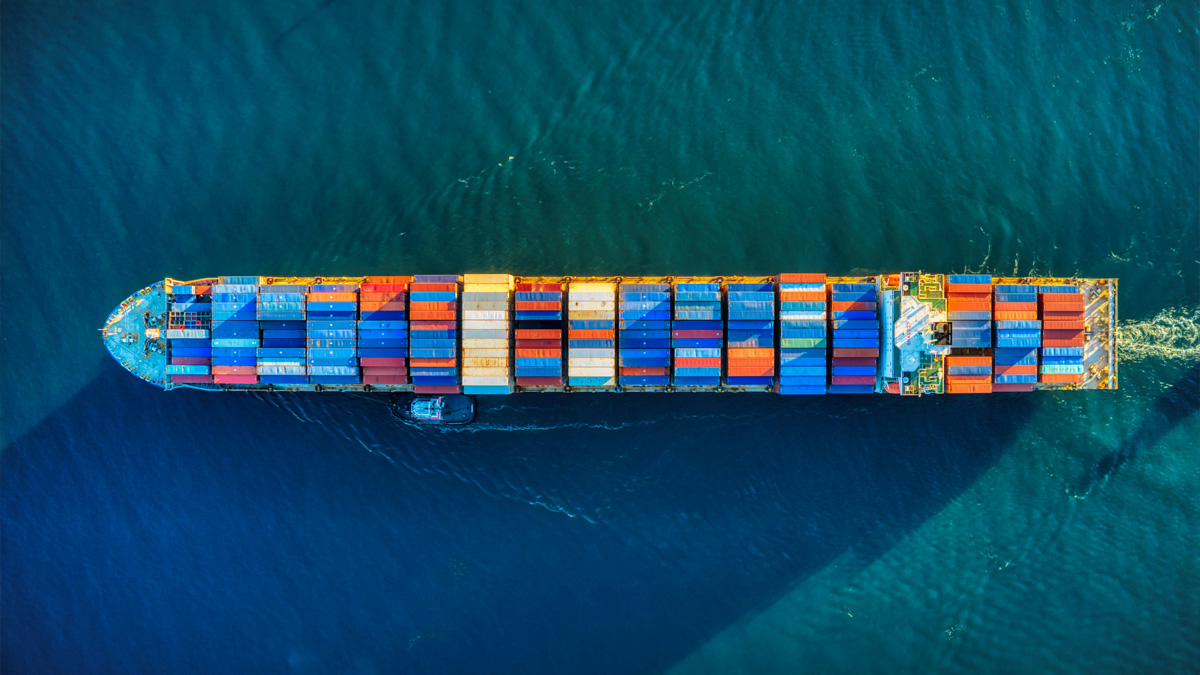
The ocean container freight industry is facing a structural turning point as slowing demand growth collides with increasing vessel supply. New ships ordered during the pandemic boom are entering service, creating excess capacity that is pushing freight rates lower on many trade lanes.
Consolidation is accelerating in response. German container carrier Hapag-Lloyd has struck a deal to acquire Israeli carrier ZIM, cementing its position as the world's fifth-largest container shipping line. The merger reflects an industry-wide push to achieve scale economies in an environment of thinner margins.
2026 will be remembered as the year the shipping industry pivoted from pandemic-era disruption management to a new era of structural adaptation — balancing overcapacity, digital transformation, and geopolitical risk.
AI and Automation Transform Operations
Logistics providers are aggressively investing in artificial intelligence and automation to improve efficiency and decision-making. Key areas of investment include warehouse robotics, digital freight platforms offering end-to-end shipment visibility, and AI-driven demand forecasting that helps optimise routing and capacity allocation.
These technology investments are being driven by necessity as much as ambition. Labour shortages, rising operational costs, and the complexity of managing increasingly fragmented supply chains are pushing companies to automate processes that were previously handled manually.
Tariffs, Costs, and Policy Uncertainty
Tariff uncertainty remains a major challenge for global trade in 2026. Nearshoring trends are reshaping traditional trade routes, as companies seek to reduce their exposure to tariff risk by moving production closer to end markets. This shift is creating new demand patterns that the logistics industry is still adapting to.
On the domestic front, shippers are facing escalating costs. FedEx and UPS have both implemented additional rate and surcharge increases in 2026, with last-mile delivery costs rising particularly sharply. Meanwhile, the U.S. Highway Trust Fund is set to expire on September 30, 2026, creating uncertainty around transportation infrastructure funding.
Looking Ahead
The mid-year outlook suggests that while the industry is stabilising, challenges persist. Environmental, social, and governance (ESG) requirements are adding new compliance costs, while the need for risk management capabilities has never been greater. Companies that can combine operational efficiency with digital agility are best positioned to navigate the evolving landscape.
Sources:
Supply Chain Dive — 5 Logistics Trends to Watch in 2026
UPS Supply Chain Solutions — Q2 2026 Global Freight & Logistics Trends
WWEX Group — 2026 Shipping and Logistics Report
Worldwide Express — Mid-Year Shipping Trends 2026
iContainers — Global Logistics Market Trends 2026
More Than Shipping — 2026 Ocean Freight Outlook